The truth about your claim, up front.
Roof Insurance Claims in Winston-Salem, NC
Honest, end-to-end help documenting storm damage and working with your adjuster — for homeowners across the Triad.
Insurance Claim Management
The short version
- An inspection before you file
- Never a promise of approval
- Photo documentation and adjuster coordination
Serving Winston-Salem, Greensboro, Kernersville, High Point NC · (336) 505-7977
Start to Finish
How it works
-
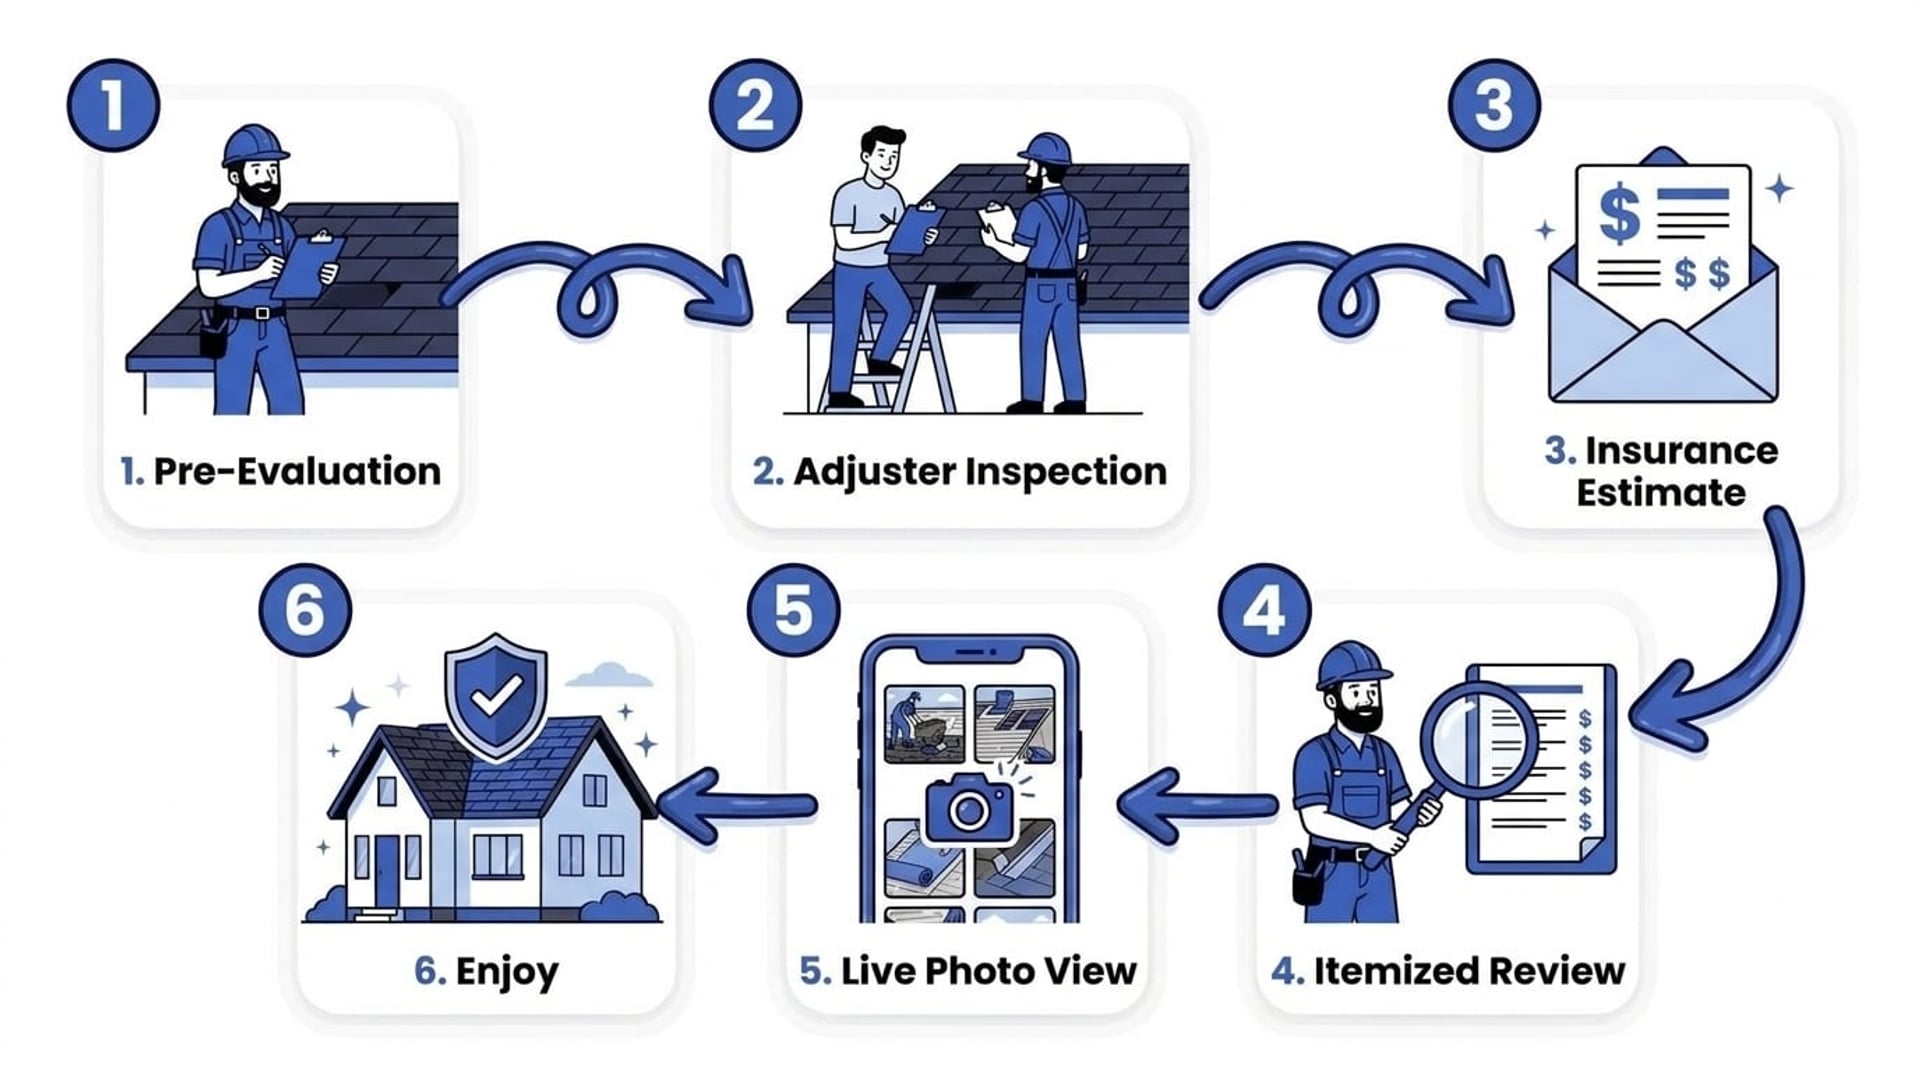
Inspect first
A professional look before you ever open a claim.
-
Honest read
Storm damage or wear and age, and what that means for coverage.
-
Document it
Thorough photos and a scope that reflects the real damage.
-
Work with your adjuster
We help you understand your policy and deductible along the way.
Insurance claims, handled honestly
The insurance process is confusing and stressful — and plenty of roofers take advantage of that. We do the opposite. Blue Hat Roofing guides homeowners in Winston-Salem, Greensboro, Kernersville, and High Point NC through every step of a roof insurance claim, and we lead with the truth about whether you actually have a covered claim.
What honest claim help looks like
- Thorough inspection and photo documentation of the actual damage.
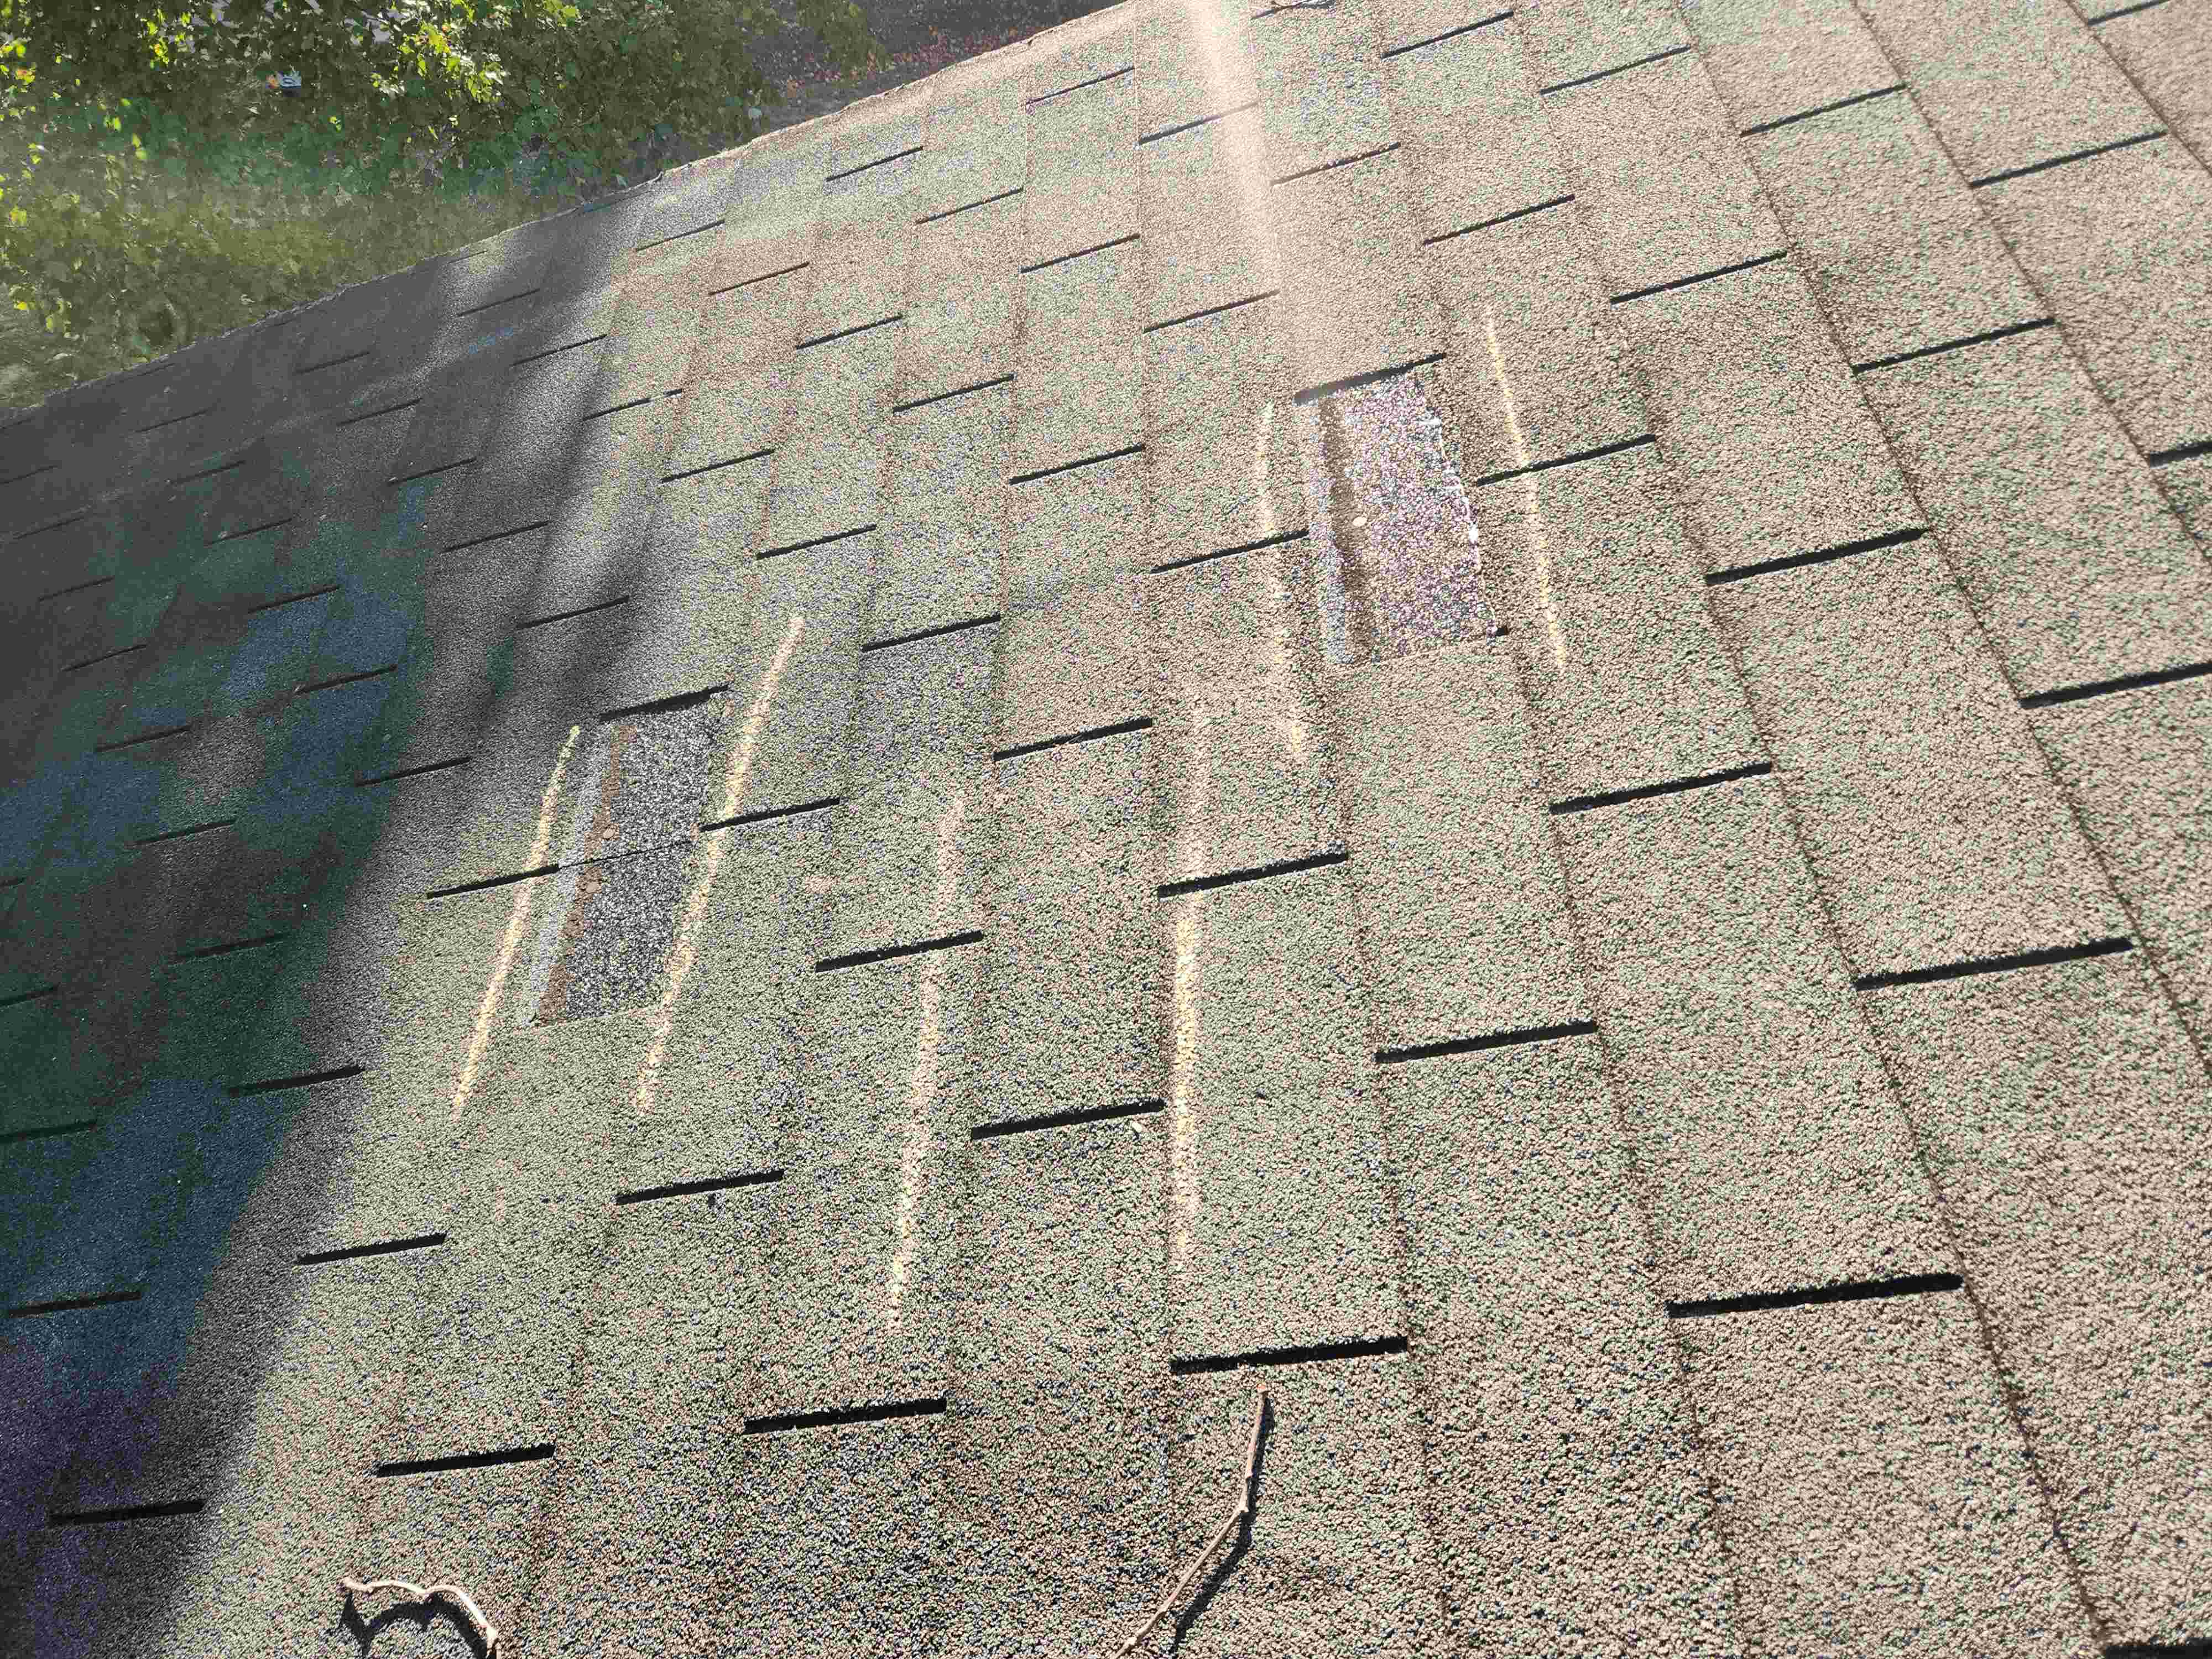
- Straight answers on whether your damage is storm-related (covered) or wear/age (not covered).
- Adjuster coordination so the scope of work reflects the real damage.
- Help understanding your policy and deductible before you commit.
The honest-approach difference
We will never suggest you file a claim without legitimate storm damage, and we will never imply we can guarantee approval — no roofer can. If a claim is unlikely to be approved, we'll tell you, and we'll recommend a professional inspection before you ever file so a denied claim doesn't end up on your record.
Storm damage vs. wear and tear
Covered claims come from sudden events — hail, high wind, fallen limbs. Gradual aging, granule loss from years of UV exposure, and deferred maintenance generally are not covered. We help you understand which one you're actually dealing with. Call (336) 505-7977 for an honest inspection.
After a storm: the North Carolina claim steps
The NC Department of Insurance publishes its own guidance on what to do after a loss. Here is how it works in plain words:
- Contact your agent or insurance company right away.
- Make reasonable emergency repairs, such as a tarp, to prevent more damage, and keep your receipts.
- Photograph the damage before and after emergency repairs, and make a list of damaged property.
- Don’t make extensive repairs before the adjuster inspects.
- Expect an estimate of loss. The adjuster prepares one and may ask you for a proof of loss.
- Mind the replacement-cost deadline. With replacement-cost coverage, you need to provide proof of replacement within 180 days of the date of loss to collect the full replacement cost.
Stay off the roof while you wait. Check from the ground with binoculars and call a professional. Our guides on how to check your roof after a Triad storm and what tornadoes and strong winds do to a roof cover the signs to look for.
Ask about like-kind-and-quality
Here is how policies typically work, and what to ask your adjuster or agent. This is Blue Hat guidance, not North Carolina law, and every policy is different. If a component was on your old roof, such as drip edge, starter strip, or ridge vents, your policy should generally cover replacing it with like-kind-and-quality materials. Read your policy, then ask your adjuster or agent how it handles each item, and make sure the scope of work lists every component being replaced. We can’t promise what an insurance company will approve, but we can help you understand the estimate and what to ask.
Questions & Answers
Frequently Asked Questions
Will my insurance actually cover roof damage?
Insurance typically covers sudden storm damage — hail, wind, fallen limbs — but not gradual wear, age, or neglect. We inspect first and tell you honestly whether your damage is likely to be a covered claim before you file.
Do you guarantee my claim will be approved?
No — and be cautious of anyone who does. We can’t control an insurance company’s decision. What we can do is document the damage thoroughly, represent it accurately, and give you an honest assessment of your odds up front.
What does your insurance claim help include?
A detailed inspection with photo documentation, help understanding your policy and deductible, coordination with your adjuster, and a scope of work that reflects the actual damage — end to end.
Should I file a claim before or after you inspect?
We always recommend a professional inspection first. That way you know whether you have legitimate, covered damage before you open a claim — which protects your claim history.
What if you find the damage isn’t claim-worthy?
We’ll tell you plainly. If a claim is unlikely to be approved, we’d rather save you the time and the mark on your record and talk through repair or replacement options instead.
Which areas do you serve for insurance claim help?
Winston-Salem, Greensboro, Kernersville, High Point, and the surrounding Triad area of North Carolina.
What should I do first after a storm damages my roof?
The NC Department of Insurance advises contacting your agent or insurance company right away, making reasonable emergency repairs such as a tarp to prevent more damage (and keeping the receipts), and photographing the damage before and after those repairs. Don’t make extensive repairs before the adjuster inspects.
How long do I have to file a roof claim in North Carolina?
Deadlines depend on your policy, so read it and call your agent or insurer promptly. The NC Department of Insurance also notes that with replacement-cost coverage you need to provide proof of replacement within 180 days of the date of loss to collect the full replacement cost.
Will my insurance pay to replace drip edge, starter strip, and ridge vents?
In general, if a component was on your old roof, your policy should cover replacing it with like-kind-and-quality materials. How your policy handles this varies, so read it and ask your adjuster or agent. This is our guidance on how policies typically work, not a promise of coverage.